Introduction
A credit card can make a large purchase feel easy.
A ₹60,000 laptop, ₹45,000 smartphone, ₹80,000 appliance, or ₹1,20,000 family purchase can look much more affordable when the amount is divided into monthly EMIs.
For example:
₹60,000 purchase → 6-month EMI → manageable monthly payment
But there is an important question:
Is the EMI actually affordable, or does it simply make an expensive purchase look affordable?
This is where credit card EMI needs careful attention.
Table of Contents
A credit card EMI converts an eligible credit-card purchase, or sometimes an existing outstanding amount, into a series of instalments. Depending on the offer, you may pay interest, a processing fee, taxes and other applicable charges.
Some offers are promoted as “No-Cost EMI”. However, “no-cost” does not automatically mean that the transaction has no cost at all. RBI requires card issuers to clearly indicate the principal, interest and upfront discount where applicable, and says an EMI with an interest component should not be disguised as a zero-interest/no-cost EMI.
The purpose of this article is not to say that credit-card EMI is good or bad.
Instead, we will look at:
- What credit-card EMI means
- How it works
- When it can help
- When it can hurt
- How to calculate the real cost
- What “No-Cost EMI” means
- Common mistakes
- EMI-related scams
- How to protect yourself
- What to do if you become a victim
- Important FAQs
What Is Credit Card EMI?
EMI means Equated Monthly Instalment.
Instead of paying the entire purchase amount immediately, the eligible amount is divided into regular instalments over a selected period.
For example:
Suppose you purchase a refrigerator for:
₹60,000
You choose a:
6-month EMI
The amount is then repaid through monthly instalments according to the applicable EMI terms.
The important point is that your actual cost may not simply be:
₹60,000 ÷ 6 = ₹10,000
Depending on the offer, there may be:
- Interest
- Processing fee
- GST/taxes on applicable charges
- Foreclosure/pre-closure charges
- Other applicable fees
Therefore, always check the total payable amount, not just the monthly EMI.
How Does Credit Card EMI Work?
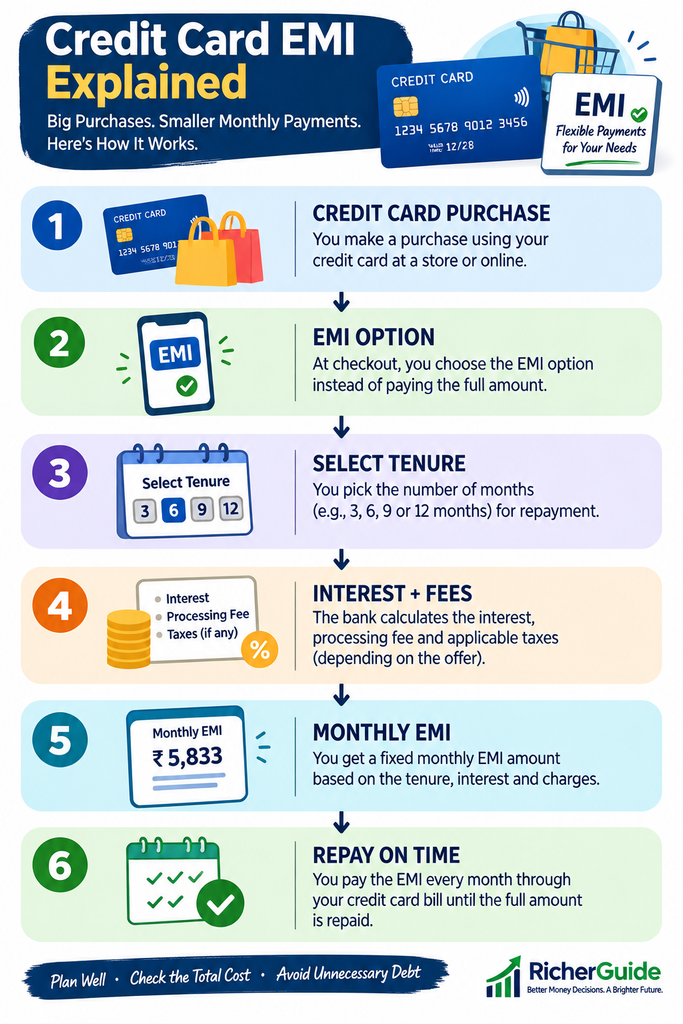
A simple credit-card EMI flow looks like this:
              PURCHASE
                 ↓
        ₹60,000 PRODUCT
                 ↓
       EMI OPTION AVAILABLE
                 ↓
       SELECT EMI TENURE
                 ↓
      INTEREST / DISCOUNT /
       FEES ARE CALCULATED
                 ↓
          EMI CREATED
                 ↓
       MONTHLY BILLING
                 ↓
       PAY EMI ON TIME
                 ↓
       EMI ENDS AFTER TENURE
Example
Imagine you purchase a television for ₹60,000.
You select a 6-month EMI.
The card issuer may calculate:
- Principal
- Interest
- Processing fee
- Applicable taxes
Your monthly statement may then include the EMI amount and applicable charges.
The exact calculation depends on the issuer and offer.
Why Do People Choose Credit Card EMI?
The biggest attraction is cash-flow management.
Imagine someone needs a ₹75,000 laptop for work.
Paying ₹75,000 at once could significantly reduce their savings.
If an appropriate EMI option is available, spreading the payment over several months may make the cash flow easier.
But there is an important distinction:
EMI can make payment easier.
It does not necessarily make the purchase cheaper.
This difference is extremely important.
When Credit Card EMI Can Help
Credit-card EMI may be useful in certain situations.
When the Purchase Is Necessary
Suppose your refrigerator stops working and replacement is necessary.
You have enough income to comfortably handle the monthly payment, but paying the entire amount immediately would disrupt your emergency savings.
An EMI could help spread the expense.
The key is that the purchase should be necessary and affordable.
When You Have a Stable Income
An EMI is a future commitment.
Before choosing it, ask:
“Will I comfortably have this money available every month?”
If your income is stable and the EMI fits comfortably within your budget, the payment may be easier to manage.
When the Total Cost Is Reasonable
Compare:
Option A: Pay immediately
Option B: Credit-card EMI
Option C: Another legitimate financing option
Don’t compare only monthly payments.
Compare:
Total amount paid
That is the number that matters.
When It Protects Your Emergency Fund
Suppose you have ₹2 lakh in savings.
A necessary purchase costs ₹80,000.
Paying the entire amount would leave you with ₹1.2 lakh.
If a reasonably priced EMI lets you preserve sufficient emergency liquidity while keeping the monthly payment comfortable, it may be worth considering.
However, this should not become an excuse to maintain unnecessary debt.
When Credit Card EMI Can Hurt
Credit-card EMI becomes risky when the monthly payment looks small but the overall financial commitment becomes large.
When You Buy Something You Cannot Afford
This is one of the biggest problems.
Consider:
Smartphone = ₹1,00,000
The advertisement says:
“Only ₹8,333 per month!”
The monthly number may look attractive.
But the better question is:
Can I actually afford a ₹1 lakh phone?
EMI can reduce the psychological impact of a large purchase.
That can encourage overspending.
When You Have Multiple EMIs
One EMI may appear manageable.
But consider:
| Purchase | Monthly EMI |
|---|---|
| Smartphone | ₹4,500 |
| Laptop | ₹5,000 |
| Furniture | ₹3,500 |
| Appliance | ₹4,000 |
| Total | ₹17,000 |
Suddenly, your monthly commitment is ₹17,000.
This is why you should calculate your total monthly debt/EMI obligation, not evaluate each EMI separately.
When Interest and Fees Are Ignored
A ₹50,000 purchase does not necessarily cost ₹50,000 after EMI charges.
For example:
| Component | Example |
|---|---|
| Purchase price | ₹50,000 |
| Interest | ₹3,000 |
| Processing fee | ₹999 |
| Applicable taxes | ₹180 |
| Approx. total | ₹54,179 |
Illustration only. Actual charges vary by issuer and offer.
The EMI may look affordable while the total cost is higher.
When You Only Look at the Minimum Due
This is a major credit-card mistake.
Minimum Amount Due is not the same as paying your bill in full.
RBI requires card issuers to warn customers that paying only the minimum amount can stretch repayment over months or years and result in compounded interest on outstanding balances.
If you have an EMI plus other regular credit-card purchases, failing to manage the full statement can become expensive.
When EMI Is Used for Lifestyle Spending
A holiday, luxury watch, expensive restaurant bill or unnecessary upgrade may feel affordable because of EMI.
But ask:
“Would I still buy this if I had to pay the full amount today?”
If the answer is no, the EMI may be hiding an affordability problem rather than solving one.
What Is No-Cost EMI?
No-Cost EMI is a common promotional offer.
The basic idea is that the customer does not bear the advertised interest cost in the usual way because the economics of the offer may involve a merchant discount, upfront discount or other arrangement.
But you should not assume:
No-Cost EMI = Absolutely No Additional Cost
RBI specifically requires transparency when credit-card transactions are converted to EMI. The principal, interest and upfront discount provided by the merchant/card issuer to make an offer “no cost” should be clearly indicated before conversion and separately reflected in the card statement. An interest-bearing EMI should not be presented as a zero-interest/no-cost EMI.
Therefore, check:
- Product price
- EMI amount
- Number of EMIs
- Processing fee
- GST/taxes
- Upfront discount
- Cashback conditions
- Cancellation/refund conditions
- Pre-closure charges
- Any other applicable fee
The Real Cost of Credit Card EMI
A simple formula can help:
REAL EMI COST

Purchase Price
       +
Interest
       +
Processing Fee
       +
Applicable Taxes/Charges
       +
Other Applicable Fees
       -
Genuine Discounts/Cashback
       =
TOTAL COST
For example:
Purchase
₹80,000
Interest
₹4,000
Processing fee
₹999
Applicable tax on fee/interest as applicable
₹180
Genuine discount
₹2,000
Then:
₹80,000 + ₹4,000 + ₹999 + ₹180 − ₹2,000
= ₹83,179
So the purchase effectively costs about ₹83,179, based on these illustrative assumptions.
Always use the actual figures from your card issuer.
Credit Card EMI Calculator
You can use a simple EMI calculation for a typical reducing-balance loan:
EMI formula
EMI = P × r × (1+r)ⁿ / [(1+r)ⁿ − 1]
Where:
- P = principal amount
- r = monthly interest rate
- n = number of months
Example
Suppose:
- Principal = ₹60,000
- Annual interest rate = 18%
- Monthly rate = 18% ÷ 12 = 1.5%
- Tenure = 6 months
The approximate EMI is:
₹10,526 per month
Approximate total EMI payments:
₹63,156
Approximate interest:
₹3,156
This is only an illustration. Credit-card EMI products may use issuer-specific calculations and may also include processing fees and taxes.
Important
Don’t rely on a generic EMI calculator alone.
Use your issuer’s actual EMI disclosure to determine your final payable amount.
EMI Comparison Table
Suppose you need to finance ₹60,000.
Here is an illustrative comparison:
| Tenure | Approx. Monthly EMI* | Approx. Total EMI Payment* |
|---|---|---|
| 3 months | ₹20,405 | ₹61,215 |
| 6 months | ₹10,526 | ₹63,156 |
| 9 months | ₹7,233 | ₹65,097 |
| 12 months | ₹5,501 | ₹66,012 |
*Illustration assuming 18% annual reducing-balance interest and excluding processing fees/taxes.
What does this show?
A longer tenure generally reduces the monthly EMI.
But it can increase the total interest paid.
Therefore:
Lower EMI does not automatically mean lower cost.
A Simple EMI Cost Chart
MONTHLY EMI vs TOTAL INTEREST

Short Tenure
     ↓
Higher Monthly Payment
     ↓
Usually Lower Total Interest

Long Tenure
     ↓
Lower Monthly Payment
     ↓
Potentially Higher Total Interest
Think of the trade-off as:
Lower monthly burden ↔ potentially higher total cost
The right choice depends on your cash flow and the actual offer.
Real-Life Example: When EMI Helps
Meet Anita.
She needs a laptop costing:
₹72,000
The laptop is necessary for her work.
She has:
₹2,00,000 emergency savings
If she pays ₹72,000 immediately, her liquid savings reduce substantially.
She finds a transparent 6-month EMI option with manageable charges.
Her monthly income is stable.
Her existing EMI commitments are low.
She checks the:
- Interest
- Processing fee
- Total payable
- Tenure
- Cancellation rules
She determines that the monthly payment comfortably fits her budget.
In this situation, EMI can function as a cash-flow management tool.
The important point is not simply that she chose EMI.
She first checked affordability and total cost.
Real-Life Example: When EMI Hurts
Now consider Rahul.
His monthly take-home income is:
₹50,000
He already has:
- Phone EMI = ₹4,000
- Bike EMI = ₹6,000
- Personal loan EMI = ₹5,000
Existing monthly commitments:
₹15,000
He then buys a ₹90,000 television on credit-card EMI.
New EMI:
₹7,500
Total monthly debt commitments:
₹22,500
That means almost half of his ₹50,000 monthly income is now committed to these payments.
Then an unexpected medical or household expense occurs.
He struggles to pay his credit-card bill.
The EMI that initially looked small has now contributed to a much tighter monthly cash flow.
Lesson
Always calculate your total EMI burden before taking another EMI.
How EMI Can Affect Your Credit Card Limit
Suppose your credit-card limit is:
₹2,00,000
You make a large ₹80,000 purchase and convert it into EMI.
Depending on the issuer’s terms, the transaction can affect your available credit limit, with the limit becoming available again as payments are made.
This means EMI does not necessarily mean that your credit limit immediately becomes completely free.
A large EMI purchase can therefore reduce the amount of credit available for other purchases.
This is another reason to avoid treating your credit limit as additional income.
Common Credit Card EMI Mistakes
Mistake 1: Looking only at EMI
Wrong approach:
“₹4,999 per month is affordable.”
Better approach:
“What is the total amount I will pay?”
Mistake 2: Ignoring processing fees
A small processing fee can increase the effective cost.
Mistake 3: Choosing the longest tenure automatically
Longer tenure can reduce monthly payment but may increase total interest.
Mistake 4: Having too many EMIs
Multiple small EMIs can become one large monthly obligation.
Mistake 5: Using EMI for every purchase
EMI should not become your default payment method.
Mistake 6: Assuming “No-Cost” means no conditions
Read the complete offer.
Mistake 7: Missing payment dates
Late payment can result in charges and may affect your credit profile depending on the circumstances.
Mistake 8: Ignoring other card spending
Remember that your credit-card statement can contain:
- EMI
- Regular purchases
- Fees
- Taxes
- Other charges
Review the entire statement.
How to Decide: Should You Take the EMI?
Use this simple five-question test.
1. Is the purchase necessary or genuinely useful?
If not, wait.
2. Can I afford the total cost?
Not just the EMI.
3. Will the EMI comfortably fit my monthly budget?
Calculate it before buying.
4. Do I understand every fee?
Check the terms.
5. Do I already have several EMIs?
If yes, calculate your combined monthly obligation first.
A Simple Credit Card EMI Decision Flow
             DO I NEED THE PURCHASE?
                     |
             ┌───────┴───────┐
            NO              YES
             ↓                ↓
          WAIT        CAN I AFFORD IT?
                            |
                     ┌──────┴──────┐
                    NO            YES
                     ↓              ↓
                   WAIT      CHECK TOTAL COST
                                  |
                           ┌──────┴──────┐
                          HIGH          REASONABLE
                           ↓               ↓
                         COMPARE       CHECK EMI
                                         |
                                  FITS BUDGET?
                                         |
                              ┌──────────┴─────────┐
                             NO                    YES
                              ↓                      ↓
                            WAIT             REVIEW TERMS
                                                    ↓
                                             MAKE INFORMED
                                               DECISION
EMI-Related Scams: What Is the Scam?
Credit-card EMI itself is not a scam.
However, scammers can use EMI offers as bait.
For example, you may receive a fake message:
“Congratulations! Your credit card is eligible for ₹2 lakh instant EMI at 0% interest. Click here to activate.”
The link may lead to a fake website.
The scammer may ask for:
- Card number
- Expiry date
- CVV
- OTP
- PIN
- Internet banking password
- Personal information
Once the information is shared, the criminal may attempt an unauthorised transaction.
Important rule
A genuine EMI offer does not require you to share your OTP, PIN or password with an unknown person.
How EMI Scammers Operate Step by Step
A typical scam may look like this:
FAKE EMI OFFER
      ↓
SMS / CALL / WHATSAPP
      ↓
“LIMITED TIME” MESSAGE
      ↓
FAKE LINK OR PHONE NUMBER
      ↓
REQUEST FOR CARD DETAILS
      ↓
REQUEST FOR OTP / PIN
      ↓
UNAUTHORISED TRANSACTION
      ↓
FINANCIAL LOSS
Step 1: Fake offer
The scammer promises:
- Zero-interest EMI
- Instant EMI conversion
- Higher credit limit
- EMI cancellation
- Refund
- Special bank offer
Step 2: Urgency
The scammer says:
“Offer expires today.”
or:
“Your EMI will be cancelled if you don’t verify immediately.”
Step 3: Fake verification
They may send a link or ask you to install an application.
Step 4: Credential theft
The victim is asked for sensitive card or banking details.
Step 5: OTP request
The scammer may ask for the OTP to “activate” the EMI.
Step 6: Unauthorised transaction
The information may be used to initiate a transaction.
Warning Signs of an EMI Scam
Watch out for these red flags:
1. Unexpected EMI offer
You did not apply for anything, but someone says you have been approved.
2. Pressure to act immediately
“Only 10 minutes remaining!”
3. Request for OTP
Never share an OTP with an unknown caller.
4. Request for PIN
A genuine bank representative should not need your card PIN.
5. Suspicious link
Be careful with shortened or unfamiliar URLs.
6. Remote-access application
Do not install unknown apps because someone claims they are required to process EMI.
7. Payment to unlock EMI
Be cautious if someone asks you to transfer money to activate or cancel an EMI.
8. Fake customer-care number
Always obtain customer-care details from your card issuer’s official website/app or the back of the card.
How to Protect Yourself
Rule 1: Verify through the official bank app
If you receive an EMI offer, open your bank’s official app independently.
Don’t use the link sent by an unknown person.
Rule 2: Never share your OTP
Your OTP is for authentication.
Treat it as confidential.
Rule 3: Never share your PIN
Your card PIN should remain private.
Rule 4: Check the transaction before approving
Read the amount and merchant information carefully.
Rule 5: Save EMI documentation
Keep:
- Offer details
- EMI confirmation
- Order invoice
- Bank communication
- Payment records
Rule 6: Monitor your statements
Check your credit-card statement regularly.
RBI requires card issuers to provide transparent information about charges and EMI conversion, including relevant principal, interest and discount information.
What to Do If You Become a Victim
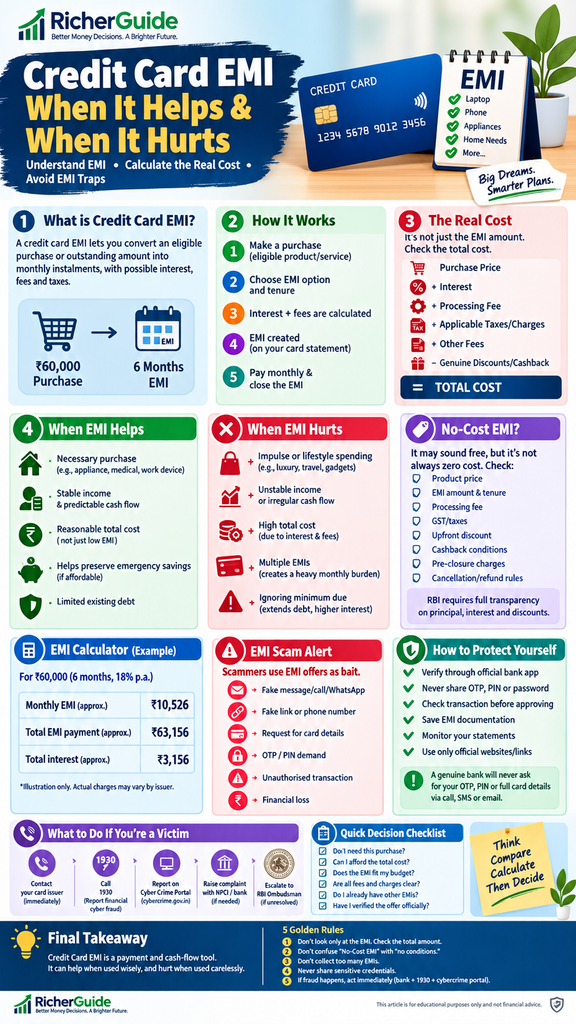
If an unauthorised transaction has occurred, act immediately.
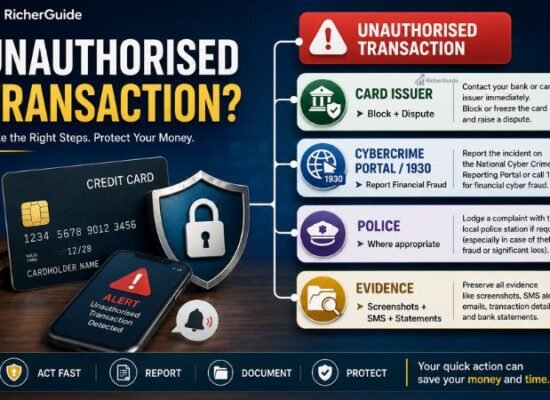
Step 1: Contact your card issuer
Use the official customer-care number or bank app.
Ask the bank to:
- Block/freeze the card if appropriate
- Report the unauthorised transaction
- Raise a dispute
- Provide a complaint/reference number
RBI requires banks to provide channels for reporting unauthorised transactions and take steps to prevent further unauthorised transactions after receiving a report.
Step 2: Call 1930
For financial cyber fraud in India, the National Cyber Crime Reporting Portal advises immediate reporting through 1930.
Step 3: Report through the Cyber Crime Portal
Use:
National Cyber Crime Reporting Portal
Keep evidence such as:
- Screenshots
- SMS
- WhatsApp messages
- Phone numbers
- Transaction IDs
- Emails
- Bank statements
- URLs
Step 4: Report through the relevant payment/bank channel
NPCI’s complaint facility notes that fraudulent, unidentified or unauthorised transactions should be raised with the respective bank for redressal.
Step 5: Escalate unresolved bank complaints
First complain to your card issuer.
Under RBI’s current grievance framework, if the regulated entity does not resolve the complaint within the applicable period or you are dissatisfied with the response, you can use the RBI Ombudsman mechanism. RBI’s Integrated Ombudsman Scheme, 2026 came into force on July 1, 2026.
RBI Complaint Management System
Official Reporting Channels
| Problem | Where to Report |
|---|---|
| Credit-card EMI issue | Your card issuer/bank |
| Unauthorised card transaction | Card issuer immediately |
| Online financial fraud | 1930 |
| Cybercrime | National Cyber Crime Reporting Portal |
| NPCI payment-related complaint | NPCI complaint facility / relevant bank |
| Unresolved regulated-entity complaint | RBI Ombudsman mechanism |
Important: For an actual fraud, don’t wait for a social-media response from the bank. Use the official emergency/reporting channel immediately.
Credit Card EMI Checklist
Before converting a purchase into EMI, check:
☐ Purchase is necessary/useful
☐ Monthly EMI fits my budget
☐ Total payable amount is known
☐ Interest rate is known
☐ Processing fee is known
☐ Taxes/charges are understood
☐ Tenure is suitable
☐ Existing EMIs have been considered
☐ Credit limit impact is understood
☐ Pre-closure rules are understood
☐ Refund/cancellation rules are understood
☐ Offer has been verified through official channels
If several boxes remain unchecked, stop and review the offer before proceeding.
Credit Card EMI: Pros and Cons
| Possible Benefit | Possible Risk |
|---|---|
| Spreads a large payment | Creates future monthly obligations |
| Can help manage cash flow | May increase total cost |
| May offer promotional pricing | Processing fees may apply |
| Predictable instalments | Multiple EMIs can strain budget |
| Can preserve liquidity for genuine needs | May encourage unnecessary purchases |
| Convenient for eligible purchases | Missed payments can create additional problems |
The important point is that the same EMI can be useful for one person’s budget and unsuitable for another.
Credit Card EMI vs Paying in Full
| Factor | Pay in Full | Credit Card EMI |
|---|---|---|
| Immediate cash outflow | Higher | Lower |
| Monthly obligation | None for that purchase | Yes |
| Interest | Usually none for purchase if paid as required | May apply |
| Processing fee | Usually not applicable to normal full payment | May apply |
| Cash-flow flexibility | Lower initially | Higher |
| Risk of over-borrowing | Lower | Can increase with multiple EMIs |
The correct comparison depends on your actual financial situation and the specific EMI terms.